
The problem with hypergrowth AI startups
X ● Covered by 3 sources
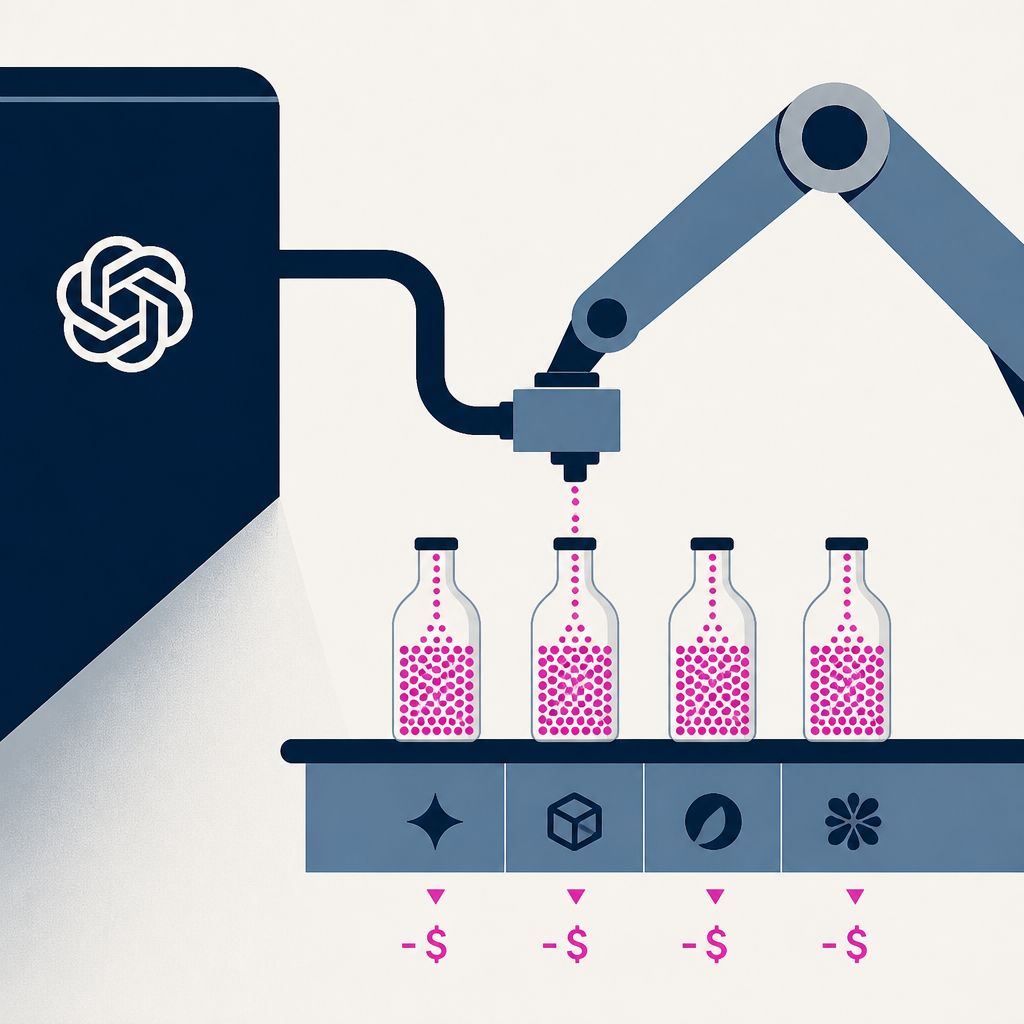
Some AI startups posting insane revenue growth are basically just reselling inference at a loss or razor-thin margins. That growth looks great on a slide but means nothing if there's no value added and no path to profit.
Based on reporting by X — read the original for the full story.
Summary, retelling and take written by AI under human oversight; images are AI-generated illustrations. How we work · Report an error
Every few weeks another AI startup shows up with a chart that looks like a hockey stick tipped on its side, and the headline is always some multiple of revenue growth that sounds absurd for a company that's barely two years old. The problem, according to a growing chorus of skeptics, is what's actually happening underneath those charts. A lot of these companies are not building anything particularly novel on top of the intelligence they're selling. They're buying inference from the big model labs, OpenAI, Anthropic, whoever, and reselling it at prices barely above cost, sometimes below it, just to keep the top-line number climbing.
That's a fundamentally different business than what venture investors think they're funding. Revenue growth is supposed to signal that a company found a market and can extract value from it. But if the margin on every dollar of revenue is thin or negative, growth isn't a sign of health, it's a sign of a subsidy. Someone is eating the cost gap, either the startup's cash reserves or its investors, and neither can do that forever without a much larger round or a real change in unit economics.
The deeper issue is value-add, or the lack of it. Wrapping an API call in a slicker interface and calling it a product used to work because the underlying models were harder to access directly. That gap is closing fast. Enterprises are getting comfortable calling foundation model APIs themselves, and the tooling to do that well is maturing month over month. So the startups whose entire pitch is convenience and packaging around someone else's intelligence are watching their moat evaporate just as fast as their revenue climbed.
None of this means every fast-growing AI company is doomed. Plenty are building genuine layers, better retrieval, domain-specific fine-tuning, workflows that actually save time rather than just routing tokens. But investors chasing growth numbers without asking about gross margin are going to get burned, and probably already are. The next twelve months will separate companies that resell intelligence from companies that actually do something with it.
My take — AI-written commentary, not fact-checked reporting
I've watched this movie before with cloud arbitrage startups a decade ago, and it ends the same way: fast growth, thin margins, and a brutal reckoning once the funding environment tightens. If your entire business is a markup on someone else's model, you're not an AI company, you're a reseller with better marketing, and the market will eventually price you like one.
Read more about this at: X